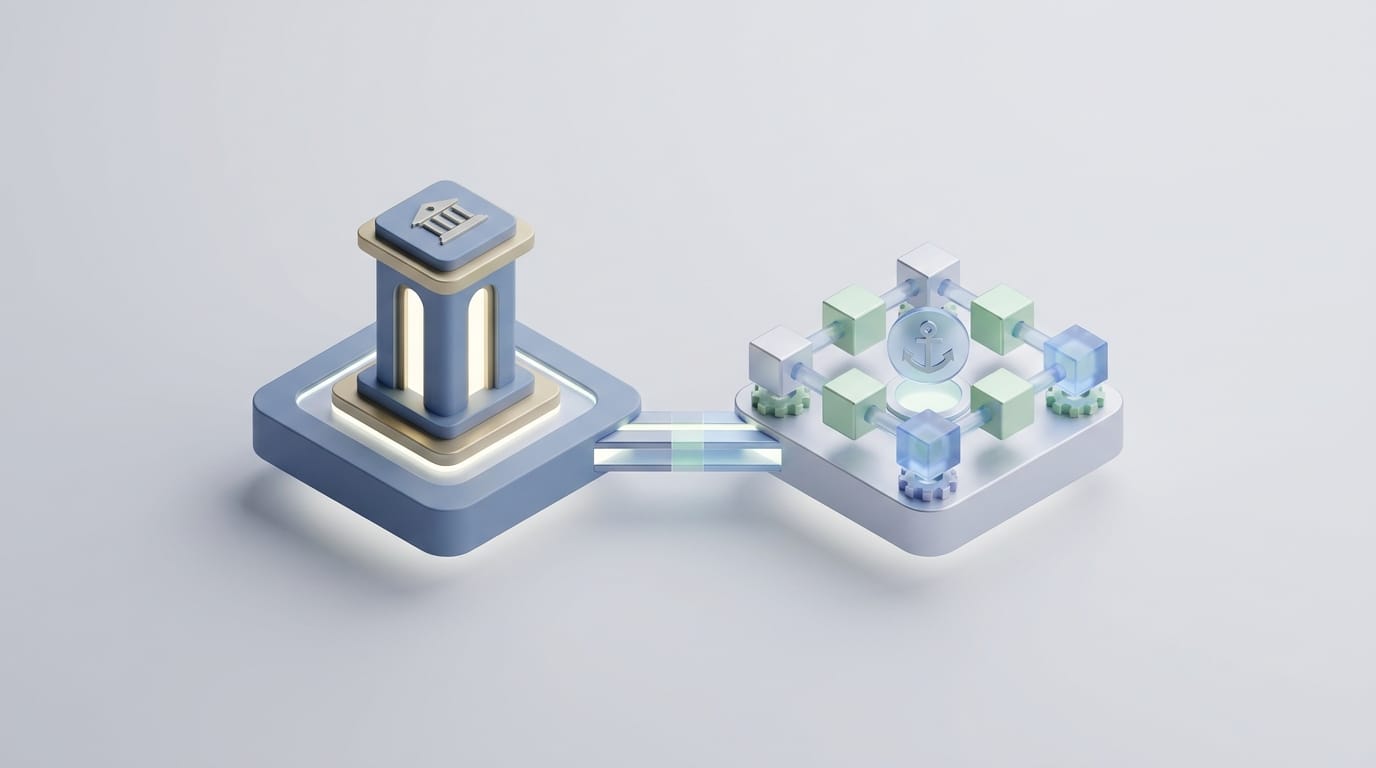
When the foundation of global finance moves from paper ledgers to programmable code, the winner depends on who controls the assets. The ongoing shift regarding cbdcs vs stablecoins changes how money crosses borders and how nations protect their power. For institutional investors and policymakers, this is no longer a theoretical debate about technology. The market has split into two paths: government-issued Central Bank Digital Currencies (CBDCs) and private stablecoins that act as the plumbing for digital trade. While both offer price stability, they differ in their legal structure, credit risk, and the goals they serve.
Understanding this system requires looking past the user interface and into the balance sheets of the issuers. One represents a direct claim on a government; the other is a private promise backed by various assets. As these two systems overlap, the tension between them redefines national influence and the nature of global liquidity. The outcome will decide if the future of money remains a state-run utility or becomes a private market product.
The Structural Divide Between Public and Private Digital Assets
The primary distinction in the debate over cbdcs vs stablecoins lies in the nature of the liability. A CBDC is a digital version of a national currency issued directly by a central bank. It serves as the digital equivalent of physical cash, making it a direct liability of the state. Because it exists on the central bank’s own ledger, it carries no credit risk. No middleman can go bankrupt and prevent you from accessing your funds.
Direct Liability Versus Private Promises
Stablecoins are private obligations. When a user holds a stablecoin like USDC or USDT, they hold a receipt for assets kept in reserve by a private company. These reserves usually consist of short-term government bonds, bank deposits, and other liquid tools. While the goal is to maintain a 1:1 value with a currency like the dollar, the user faces the credit risk of the company and its banking partners. This structure makes them function more like money market funds than sovereign money.
Settlement Finality in Digital Markets
The way these assets settle also differs. CBDC transactions settle in central bank money, which is the final form of payment in any economy. In the private sector, stablecoin transactions settle on blockchains where finality depends on the rules of the network. For large markets, the shift toward simultaneous exchange of assets and payment often requires central bank reserves to remove the risks associated with time delays in international transfers. This ensures that when a trade happens, the value moves instantly without the danger of a bank failing in the middle of the process.
The Geopolitics of CBDCs vs Stablecoins
Central banks do not build digital currencies just to modernize their systems; they do so to protect their interest rate cycles. If private digital assets replace the local currency for daily use, a central bank loses its power to influence the economy. When a population uses a foreign-issued stablecoin for everything from coffee to rent, the local central bank can no longer use its own rates to slow down inflation or encourage growth.
Retaining Control Over Domestic Economies
The risk of digital dollarization is high in emerging markets. When a local currency is unstable, citizens naturally look for safety. In recent years, people in countries like Argentina have processed billions in stablecoin transactions to hedge against high inflation, according to research by Tazapay. By issuing a CBDC, a central bank provides a legal digital alternative that ensures the local currency remains the primary unit of account within its borders. This keeps the state in control of the financial environment during times of stress.
Preventing Private Financial Contagion
Central banks also view private stablecoins as a potential threat to financial stability. If a major stablecoin were to suffer a run or if its collateral failed, the damage could spread to the traditional banking system. CBDCs act as a defensive measure by providing a public space for digital payments that does not rely on the profit motives or operational success of a private company. This ensures that even in a crisis, the basic payment systems of the nation remain functional and available to all citizens.
Stablecoins as a Tool for Digital Expansion
The relationship between cbdcs vs stablecoins reveals a deep strategy for currency dominance. In some regions, the law has shifted toward favoring private innovation over state-run projects. Recent legislation has prohibited the Federal Reserve from issuing a retail CBDC, which effectively outsources the digital dollar to private companies. This move allows the dollar to enter foreign markets with an agility that a government project could not match. It allows the currency to spread through private apps and global networks without the friction of official government treaties.
Exporting Influence Through Private Networks
Private stablecoins act as a vehicle for the U.S. dollar to become the primary medium of exchange in countries where banks are slow or the local currency is failing. Because these assets live on borderless blockchains, they bypass the political and legal trouble of setting up formal banking ties. This enables real currency valuation through direct demand rather than through state-run exchanges. It creates a global market where people choose the dollar because it is easier to use than their own money.
The Strategy of Private Issuance
There is also a strategic advantage for governments in using private issuers. When a company like Circle provides the tools for dollar trade in a sensitive region, it is seen as a private market action. If a central bank provided the same service directly, it would be viewed as an aggressive act of statecraft. By supporting regulated private stablecoins, a nation can maintain its status as a reserve currency provider while avoiding the surveillance and privacy complaints that follow government digital currencies. This balance keeps the currency dominant while letting the private sector handle the operational risks.
Privacy and Traceability in Digital Money
The ability to program digital money is its most useful feature and its biggest risk. Programmable money allows for smart contracts that automate payments based on specific conditions, such as releasing payment only when a shipping container arrives at a port. However, this same technology allows for a level of monitoring that physical cash never allowed. The debate over cbdcs vs stablecoins often focuses on who gets to see these transactions and how they use that data.
Physical cash provides a degree of anonymity that is hard to copy in a digital system. In a retail CBDC model, the central bank could technically keep a record of every transaction made by every citizen. This has led to strong pushback from privacy groups. Institutional investors, however, often choose regulatory clarity over anonymity. They require ownership and security systems that meet their legal requirements, making the traceability of digital assets a benefit rather than a drawback for large-scale finance.
Operational Impact on Financial Infrastructure
The real-world impact of digital assets is most visible in how money moves across borders. Traditional international transfers rely on a slow and expensive network of middleman banks. Digital assets move at the speed of the underlying ledger, regardless of whether they are sovereign or private. Projects involving multiple nations have already shown that wholesale CBDCs can reduce settlement times from days to seconds while cutting costs by half, according to reports from the International Monetary Fund. This efficiency helps international trade by freeing up capital that would otherwise be stuck in transit.
One concern for leaders is the risk that people might move all their money into a CBDC and leave commercial banks empty. This would drain the deposits that banks use to give out loans for homes and businesses. To prevent this, many nations use a two-tier model where the central bank provides the secure ledger, but private banks manage the customer service and apps. This ensures that global crypto adoption factors do not accidentally damage the lending power of the traditional banking sector.
The Future of Coexisting Digital Currencies
The outcome of this shift is unlikely to be a single winner. Instead, we are seeing a split in how these tools are used. Wholesale CBDCs are becoming the foundation for bank-to-bank trades and large government transactions because they offer the highest level of safety. Private stablecoins are becoming the internet of money, powering daily shopping and niche applications where speed and innovation are more important than government backing. The challenge for the future is making sure these different systems can work together.
A digital world where a stablecoin in one country cannot be easily swapped for a digital currency in another is no better than the slow system we have today. New messaging standards and technical bridges are being built to ensure these assets can communicate. The global financial system is moving from a bank-led model toward a ledger-led model. In this new world, the difference between a state currency and a private asset remains important for managing risk, but their functions will overlap to create a more efficient economy. The real question is whether the current dominance of the dollar will continue through private coins or if a new world of regional CBDCs will change the balance of power. The answer will define the next fifty years of financial history.